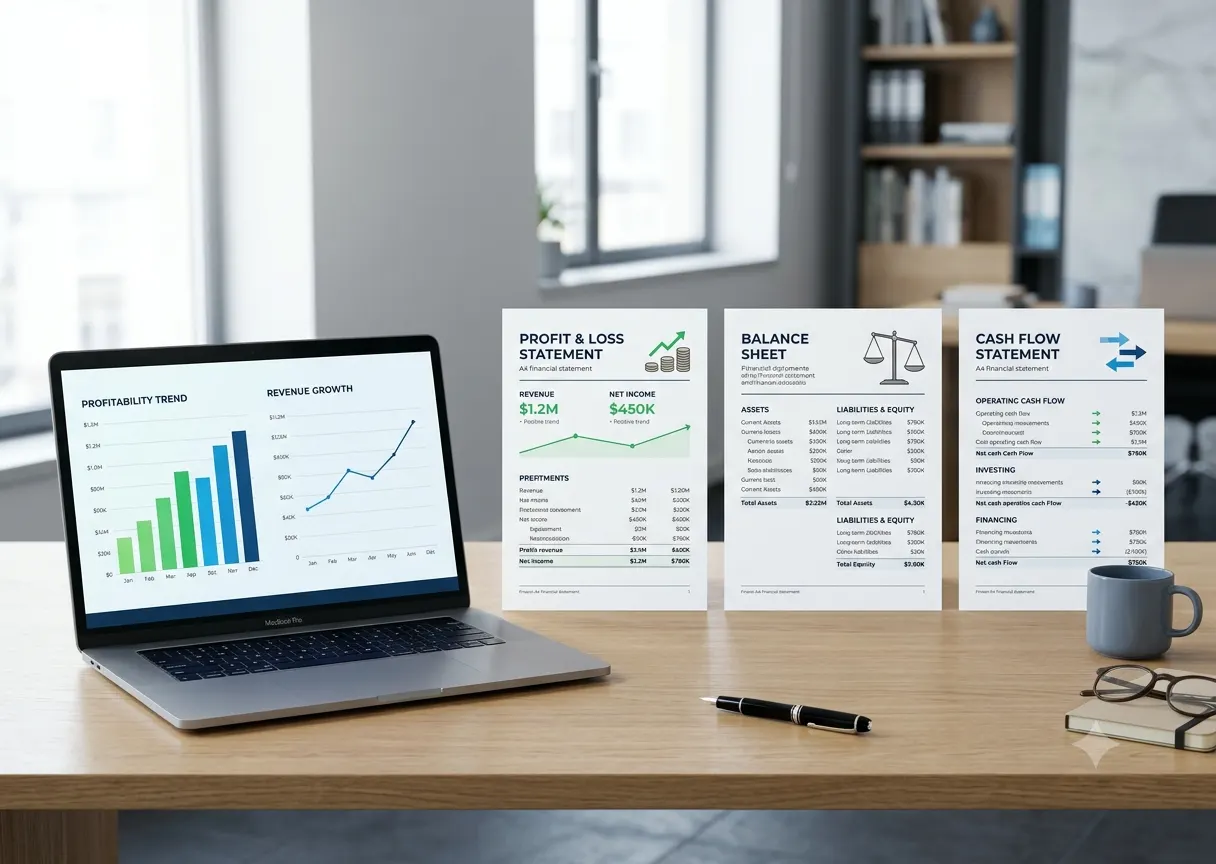
Most explanations of financial statements start with definitions, which is why most people who read them still cannot answer a basic question about a business afterwards. The statements are not three formats for presenting the same information. They answer three genuinely different questions, and the reason all three exist is that no single one of them can be trusted alone.
The profit and loss answers whether the work was worth doing
The P&L, also called the income statement, covers a period of time: a month, a quarter, a year. It records what the business earned by doing its work and what that work cost, and the difference is profit.
The line that matters most is usually not the bottom one. Gross profit, which is revenue minus the direct costs of delivering the product or service, tells you whether the core activity makes money before any of the overheads are considered. A business with weak gross margin cannot be fixed by cutting overheads, because the problem is in the work itself. A business with strong gross margin and no net profit has an overhead problem, which is an entirely different and usually easier repair.
Read the P&L as percentages of revenue rather than as amounts. Gross margin slipping from 40 per cent to 35 while revenue grows is invisible in the totals and obvious in the percentages.
The balance sheet answers what the business is standing on
Where the P&L covers a period, the balance sheet is a photograph of one moment: everything the business owns, everything it owes, and the difference between them.
It exists because profitability tells you nothing about durability. A business can post a good year while its debtors balloon, its stock ages, and its tax liabilities accrue unpaid. All three of those sit on the balance sheet and none of them appear on the P&L. Two businesses reporting identical profit can be in completely different conditions, and the balance sheet is where you find out which is which.
The cash flow statement answers whether any of it was real
This is the one people skip and the one that explains the most failures. The P&L is normally prepared on an accruals basis, which records revenue when it is earned rather than when it is paid, and costs when they are incurred rather than when they are settled. That is the correct way to measure performance, and it means reported profit and money in the bank are different numbers that can move in opposite directions.
A business can invoice a large project in March, record the profit in March, and receive nothing until June. On paper it had an excellent March. In practice it spent three months paying wages out of a shrinking balance. Growing businesses fail this way routinely, because growth consumes cash before it produces any: stock, wages and materials are all funded ahead of the payment that eventually covers them.
This is why understanding cash flow becomes especially important as a business grows, since profitability on paper does not always mean there is enough cash available to fund day-to-day needs. When Growing Businesses Need A More Strategic Financial Approach explores this issue in greater detail.
The cash flow statement traces what actually moved, and splits it into cash from operations, from investing and from financing. That split is the useful part. A business whose cash came from operations is funding itself. A business whose cash came from borrowing while operations consumed cash is doing something quite different, and the P&L will not distinguish between the two.
They only mean anything read together
Each statement is straightforward to mislead with in isolation, and the other two are what catch it.
Rising profit with falling operating cash flow means the revenue is being invoiced but not collected, and the debtors line on the balance sheet will confirm it. Healthy cash with weak profit often means the business is being funded by borrowing or by delaying its own payments, both of which show on the balance sheet as growing liabilities. Strong equity with poor cash generation usually means value is tied up in assets or stock that are not converting.
The three tie together mechanically. Profit from the P&L flows into retained earnings on the balance sheet, and the cash flow statement reconciles that profit back to the actual change in the bank balance. Where they do not reconcile, something is wrong with the records.
The few numbers worth calculating
Four calculations will tell a non-specialist most of what they need. Gross margin, as gross profit over revenue, shows whether the work itself is profitable. Debtor days, as receivables divided by revenue times 365, shows how long the business waits to be paid. The current ratio, current assets over current liabilities, shows whether short term obligations are covered. Operating cash flow compared against net profit shows whether reported earnings are converting into money.
Track those four across several periods and the direction of a business becomes readable without any accounting background.
The reason this is worth learning properly rather than approximately is that the statements are prepared for you either way. Someone in every business produces them, files them, and moves on. Whether they are ever read as information rather than as paperwork is what separates a business that is managed from one that is merely recorded. Using these numbers effectively also requires turning financial information into a practical plan, particularly around cash flow, goals, expenses, and future decisions. How to Create a Financial Plan That Actually Works provides a broader look at building that financial foundation. If you want a fuller walkthrough of the P&L specifically, Australian advisory firm Hopkan Partners has published this guide to reading each section and what it reveals.
Read More Blogs On: